Owning a home in Texas offers an incredible lifestyle and a powerful financial investment. The state’s booming real estate market attracts families and professionals from all over the country. However, Texas is also known for some of the most dynamic and severe weather patterns in the United States. From catastrophic coastal hurricanes to massive inland hailstorms and unexpected winter freezes, protecting your property requires a highly strategic approach to insurance.
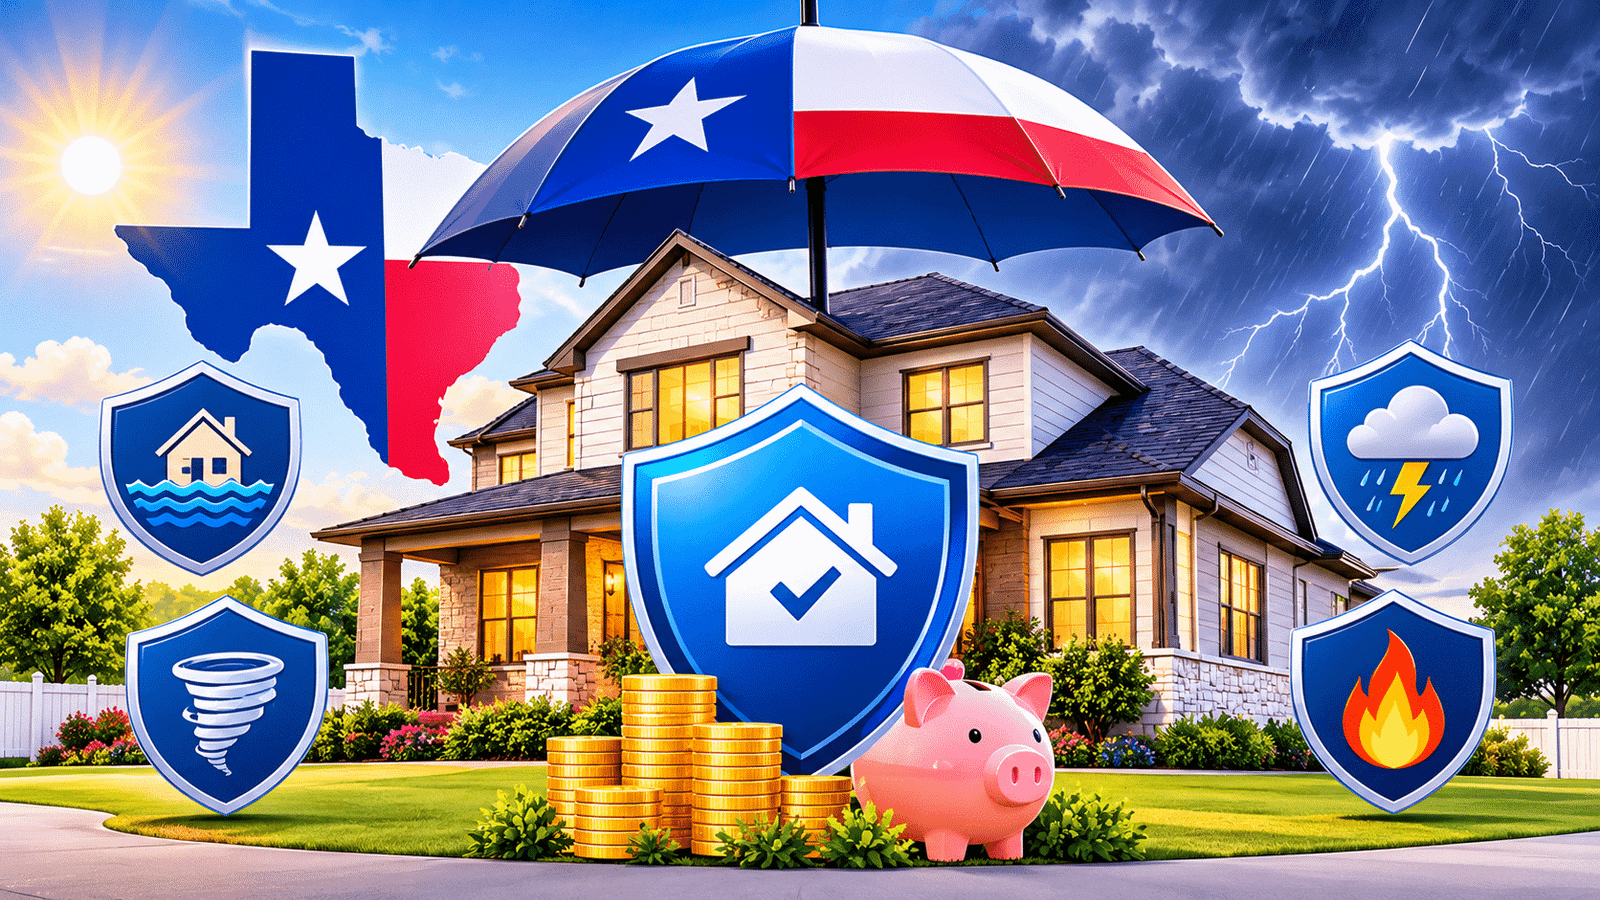
The Texas Weather Challenge
When purchasing residential property, finding the most dependable homeowners insurance Houston TX has to offer is usually the first step for Gulf Coast buyers. But standard protection must be resilient enough to handle the sheer variety of statewide weather threats.
A comprehensive home insurance policy is designed to be your primary safety net. It provides Dwelling Coverage to repair or rebuild the physical structure of your home if it is damaged by covered perils like fire, wind, lightning, or hail. It also includes Personal Property Coverage to replace your furniture, electronics, and clothing if they are destroyed or stolen. Crucially, it provides Personal Liability Protection to cover legal fees and medical bills if a guest is injured on your property and decides to sue.
The Critical Gap: What Standard Policies Exclude
The most dangerous and expensive misconception among Texas homeowners is assuming that a standard property policy covers all types of natural disasters. Standard homeowners insurance strictly excludes damage caused by rising outside water, storm surges, and overflowing bodies of water.
According to the Federal Emergency Management Agency (FEMA), just one inch of floodwater in an average-sized home can cause over $25,000 in damage. Because standard policies will not pay for this, property owners must purchase a completely separate flood insurance policy. Whether you live in a high-risk coastal zone or a supposedly low-risk inland suburb, securing flood coverage is the only way to guarantee your home is protected against Texas’s heavy seasonal rainfall and hurricane systems.
Expanding Your Personal Safety Net
As your personal wealth grows and your asset portfolio expands, the basic liability limits provided by your home policy may no longer be enough. If you are involved in a major at-fault car accident or face a massive lawsuit due to an incident at your home, your retirement savings and future wages could be heavily garnished.
To prevent financial ruin, smart homeowners add an umbrella insurance policy. Umbrella coverage sits above your underlying home and auto insurance policies, providing an extra $1 million to $5 million in liability protection for just a few hundred dollars a year. It is one of the most cost-effective ways to shield your family’s future from the unpredictable nature of lawsuits.
Finally, if you run a small business out of your home—a growing trend across Texas—your standard residential policy will not cover your commercial equipment or business liability. You must secure dedicated business insurance to ensure your home-based ente+rprise doesn’t expose your personal assets to commercial risks.
Don’t leave your biggest investment vulnerable to the next storm. Contact our agents to review your current property limits, or get a free quote to build an ironclad home and flood protection plan today.
Running a limo business in Houston?
Visit our Contact Us page today and get expert help choosing the right limousine insurance for your fleet.